
Is risk tolerance the secret to long term investing success, or simply an overlooked concept many investors misunderstand? Your comfort with volatility, your financial stability, and your investment horizon all shape how much risk you can realistically take on. Some investors thrive with aggressive portfolios that ride market swings, while others prioritise steady growth and capital protection. Want to understand where you truly stand on the risk spectrum?
Investing often feels like a conversation about returns, market cycles, and product choices, but the real anchor of every financial decision sits much deeper. It’s your personal comfort with risk. Some investors hardly blink when markets fall ten percent in a week; others lose sleep over mild volatility. That difference isn’t about knowledge or experience alone; it’s about risk tolerance, the quiet force shaping long-term investment outcomes. Risk tolerance is influenced by your age, income stability, and life stage. It evolves with your responsibilities, your goals, and even your mindset during uncertainty. Understanding it isn’t about fitting into a formula; it’s about knowing what level of fluctuation you can realistically handle while still sticking to your plan.
Why Risk Tolerance Differs Across Age, Income, and Life Stage?
- Age Shapes Recovery Time—but It’s Not the Only Factor
A younger investor may naturally lean toward growth assets because they have decades ahead of them. However, two people of the same age can still have completely different risk profiles depending on their financial reality.
- Income Stability Influences Confidence During Volatility
A professional with predictable earnings, emergency savings, and low debt can stomach drawdowns far better than someone with irregular income or heavier financial responsibilities.
- Life Stage Adjusts Your Margin for Error
Early careers often come with flexibility, fewer commitments, and room to absorb temporary losses. As families grow or as retirement approaches, the appetite for large drawdowns declines. Liquidity needs rise, and priorities shift from growth to preservation.
Risk Tolerance vs. Risk Capacity vs. Risk Required
Most investors only consider risk tolerance, but a robust strategy also accounts for:
- Risk Capacity — How much risk your finances allow you to take
Example: Two investors both say they are “aggressive,” but one has 12 months of savings, low debt, and stable income. The other supports dependents and has fluctuating earnings.
Their capacity to take risks is very different—even if their comfort level feels similar.
- Risk Required — The risk needed to reach your stated goals
Example: If you aim for $3M at retirement but invest too conservatively, your portfolio may fall short—forcing you to increase contributions or extend your working years.
Misalignment between these three is the #1 hidden reason portfolios fail long-term.
How to Practically Assess Your Own Risk Appetite?
Assessing your risk appetite begins with understanding the balance between what you want your money to achieve and how comfortably you can handle market fluctuations along the way. It requires honesty about your financial reality, awareness of your emotional responses, and clarity about the timeline of your goals. When these elements come together, they form a far more accurate picture of the level of risk you can accept without compromising your long-term plans or your peace of mind. Let us explore a structured approach for effectively evaluating personal investment risk tolerance:
- Clarify Your Time Horizon
- Time horizon determines how much volatility you can handle: Longer timelines allow investments to recover from dips, making short-term losses less damaging.
- Extended timelines reduce emotional pressure: When you know you have 10–20 years, market declines feel temporary rather than permanent.
- Short-term goals require safer choices: If you need money within 1–5 years, protecting your capital becomes more important than chasing high returns.
- Longer timelines favor growth assets: Equities become more suitable because they historically reward patience despite fluctuations.
Example: Retirement savings for a 35-year-old can endure more aggressive allocation than money needed for a home purchase in 18 months.
- Evaluate Your Financial Foundation
- A strong financial base increases confidence during downturns: Healthy savings, controlled debt, and reliable income allow you to stay invested when markets become volatile.
- Weak finances amplify perceived risk: When emergency funds or cash buffers are missing, even normal market dips feel threatening.
- Good financial stability prevents panic selling: If you are not forced to liquidate investments to cover expenses, you can ride out downturns calmly.
- Your ability to take risk depends on liquidity: The more liquid and stable your financial situation, the more risk your portfolio can sustain.
Example: Investors with 6–12 months of emergency funds typically feel far less anxious during corrections.
- Review Past Reactions to Market Drops
- Your actual behavior is the strongest indicator of tolerance: What you did in past market declines reveals genuine emotional reactions—not theoretical ones.
- Emotional responses matter more than numbers: If you felt anxious, sleepless, or rushed to sell, these are signs of lower risk tolerance.
- Positive or neutral past behavior indicates stability: If you stayed calm, held your investments, or even bought more, you likely manage volatility well.
- Patterns repeat unless addressed: Understanding past mistakes helps you avoid repeating panic-driven decisions.
- Test Hypothetical Scenarios
- Imagining severe market drops prepares you mentally: Visualizing a 15–30% decline shows whether you could realistically stay invested.
- Stress-testing reveals emotional gaps: You may think you’ll stay calm, but imagining real losses often brings out underestimated fears.
- Scenarios help align expectations with reality: They show whether your investment plan matches your true comfort level.
- Hypothetical declines highlight resilience: If you can imagine holding or rebalancing even during steep drops, you likely have strong tolerance.
Examples of Aggressive vs. Conservative Portfolios
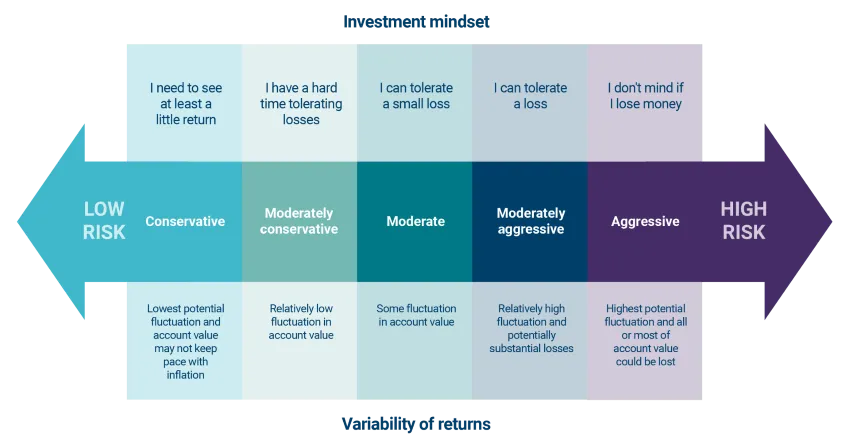
Understanding portfolio styles helps clarify how different risk levels translate into real investment choices. Conservative portfolios focus on stability and capital protection, aggressive portfolios pursue long-term growth through higher volatility, and moderate portfolios offer a balanced middle ground. Together, these categories provide a simple framework for matching your risk appetite with suitable asset allocations.
Conservative Portfolios Characteristics:
Designed to protect wealth, these portfolios emphasize stability and steady income. Most allocations sit in government bonds and high-quality corporate debt, with limited equity exposure—typically in blue-chip or dividend-paying stocks. Cash or money-market holdings add extra liquidity and safety during market downturns.
Aggressive Portfolios Characteristics:
Built for long-term growth, these portfolios accept greater volatility in exchange for higher return potential. Equities dominate—often in fast-growing sectors or emerging markets—while fixed income remains minimal. They may also include thematic or sector-driven opportunities for targeted upside.
Moderate Portfolios Characteristics:
Ideal for investors seeking growth without extreme swings, moderate portfolios blend equities and bonds in more balanced proportions. They may also incorporate select alternatives for diversification. This structure allows participation in market gains while still cushioning against sharper declines.
Conclusion
Risk tolerance is not a simple label; it’s a personal measurement of how you think, earn, react, and plan. Once you understand how much uncertainty you can genuinely handle, you can build a portfolio that sits comfortably within those boundaries. It keeps you invested longer, helps you avoid emotional decisions, and gives you the discipline needed to reach your financial goals.
How Can We Help You?
At Mighty Wisdom, we understand that navigating risk tolerance is the cornerstone of successful investing, but it’s not always straightforward. Knowing your comfort level with volatility can help you pursue higher returns, but it also prevents decisions that could jeopardize your financial goals. Striking the right balance between growth and stability is essential to building a portfolio that aligns with both your capacity and your goals.
If you’re unsure how your risk tolerance translates into an investment strategy, or how to structure a portfolio that fits your long-term objectives, we’re here to guide you. Let’s explore your options and develop a plan that is both tailored and resilient.